Solar Infrastructure Platform: 7 Essential Benefits Now
Solar Infrastructure Platform: Bridging Assets to Capital
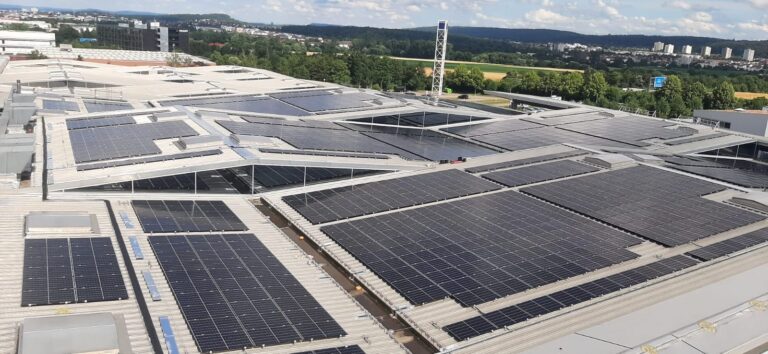
A solar infrastructure platform acts as the key layer that turns scattered rooftop installations into high-quality energy portfolios. In Europe, about 2-3 TWp of rooftop solar potential is still unused. This isn’t because of low demand or lack of ability to install, but due to a basic structural disconnect. Thousands of commercial and industrial rooftops generate clean energy daily, yet these assets remain invisible to the institutional capital seeking contracted infrastructure yield. The challenge is not technical. Panels are efficient, costs have declined, and SME adoption continues to accelerate. What the market lacks is a mechanism to aggregate these distributed assets into portfolios that behave like infrastructure rather than isolated projects. This is precisely where the solar infrastructure platform model emerges as the defining opportunity of Europe’s energy transition.
Why a Solar Infrastructure Platform Addresses Europe’s Structural Gap
Europe’s distributed solar market has scaled remarkably over the past decade. SolarPower Europe reports that the EU added about 56 GW of new solar capacity in 2023. Now, the total installed capacity is over 400 GW. More of this capacity now rests on commercial and industrial rooftops. This includes factories, warehouses, logistics centres, and retail facilities in Germany, Poland, Italy, and the Netherlands. Yet despite this growth, the market remains fundamentally fragmented.
Most rooftop installations are locally developed, independently owned, and operationally disconnected from one another. This fragmentation creates a paradox. The asset base already exists at meaningful scale, but it cannot be accessed by institutional investors seeking predictable, long-duration infrastructure exposure. Understanding the dynamics of distributed rooftop solar infrastructure in Europe reveals why aggregation has become the central challenge rather than deployment itself.
A solar infrastructure platform solves this by standardising the entire value chain. It ensures long-term rooftop access for SME building owners. It installs systems using consistent processes. It signs long-term power purchase agreements and keeps assets in a managed portfolio. The result changes distributed generation from separate projects into a valuable infrastructure asset. It offers steady cashflows and strong risk profiles that appeal to institutions.
How Solar Infrastructure Platforms Create Institutional-Grade Portfolios
The distinction between a solar project and solar infrastructure lies not in the panels themselves, but in how assets are structured, operated, and scaled. Two rooftop systems producing identical electricity can represent entirely different investment propositions. One may be a standalone installation with limited scalability and counterparty concentration. The other can sit in a varied portfolio supported by long-term contracts across different regions and buyers.
Building a Solar Infrastructure Portfolio: Institutional-Grade Assets Guide requires understanding this fundamental difference. Platform operators like ENSOOL’s distributed solar platform focus on repeatability rather than individual project optimisation. The question shifts from “how do we build this site?” to “how do we build this 500 times?” This operational philosophy determines whether distributed solar can achieve the scale and consistency that infrastructure investors require.
The execution complexity should not be underestimated. Each rooftop has unique building types, ownership structures, permit needs, and grid connection timelines. A solar infrastructure platform must systematise these variables while maintaining quality and deployment speed. When done right, the model creates portfolios with revenue visibility for 15-25 years. They have diverse counterparty exposure and meet institutional due diligence metrics.
| Characteristic | Fragmented Development Model | Solar Infrastructure Platform Model |
|---|---|---|
| Asset ownership | Individual project SPVs | Aggregated portfolio under unified structure |
| Counterparty exposure | Concentrated, single offtaker per site | Diversified across hundreds of SME offtakers |
| Scalability | Limited by deal-by-deal execution | Repeatable deployment across geographies |
| Investor accessibility | Difficult for institutional capital | Structured for infrastructure fund mandates |
| Revenue predictability | Variable, dependent on individual contracts | Long-duration PPAs with portfolio diversification |
Market Timing for Solar Infrastructure Platform Formation
Multiple forces are coming together, making now the best time to create solar infrastructure platforms in Europe. Energy price swings keep driving SMEs to adopt on-site generation. They see it as a way to manage costs, not just a sustainability effort. Grid congestion is increasing connection timelines for utility-scale projects, enhancing the relative value of distributed generation that bypasses transmission constraints. According to industry analysis,Rooftop Solar Deployment Speed: Why Distributed Beats Utility has become a meaningful competitive advantage as utility-scale queues extend for years in some markets.
Institutional capital continues seeking contracted infrastructure yield amid broader market uncertainty. Global infrastructure investment demand exceeds $15 trillion through 2040 according to Global Infrastructure Hub estimates, with energy transition assets representing a growing allocation target. Yet accessing distributed solar has historically required navigating fragmented markets with inconsistent asset quality and limited portfolio-level visibility.
The solar infrastructure platform model directly addresses this capital-asset mismatch. By aggregating rooftops into portfolios with standardised contracts, diversified counterparties, and professional asset management, platforms create investment products that fit institutional mandates. The timing is based on structure, not cycles. These market conditions will last as Europe shifts to distributed energy generation.
Frequently Asked Questions About Solar Infrastructure Platform
What makes a solar infrastructure platform different from traditional solar development?
How does a solar infrastructure platform generate returns for investors?
Which European markets are most attractive for solar infrastructure platform expansion?
What scale can a solar infrastructure platform achieve in Europe?
The structural opportunity in European distributed solar is clear. Assets exist at scale, demand from SMEs continues growing, and institutional capital seeks contracted infrastructure exposure. What has been missing is the aggregation layer that connects these elements into a functioning market. The solar infrastructure platform model represents that missing link – not as a technological innovation, but as an operational and financial structure capable of turning Europe’s fragmented rooftops into the institutional asset class the market requires.